Wednesday, February 08, 2006


Home Sweet Home

The Tax Foundation's Tax Policy Blog had two postings that shed some light on that holiest congregation of holy tax cows, the various federal income tax breaks associated with home ownership.

One posting brings to light the "tax expenditure" cost of the three principal tax breaks associated with home ownership: the home interest deduction, the deduction for state and local property taxes, and the capital gains exclusion on home sales. According to the President's budget just summited to Congress, these three items will, over the next five years, cost $863 billion.

Another post, Vertical Equity and the Home Mortgage Interest Deduction, shows dramatically that the home interest deduction, widely perceived as the deduction for "everyman" is really quite regressive:
The most recent IRS data show few low- and middle-income taxpayers benefit from the home mortgage interest deduction. Those who filed tax returns with under $30,000 in adjusted gross income (AGI) in 2003 received just 9 percent of deductions for home mortgage interest, despite filing 52 percent of all tax returns. (The median taxpayer’s AGI was approximately $29,000 in 2003.) In contrast, 36 percent of home mortgage interest deductions were claimed by taxpayers with AGIs over $100,000.
In fact, the recent run-up in real estate prices and the proliferation of McMansions can be attributed to the home interest deduction:
Despite the claims of various industry groups that the home mortgage interest deduction is an important factor promoting broad-based home ownership, IRS data show the bulk of mortgage interest deductions are claimed by a relatively small fraction of Americans with incomes well above average. As a result, it is likely that the deduction primarily encourages larger and more expensive homes among a relatively small share of taxpayers, rather than promoting broad-based home ownership among ordinary Americans.

Friday, February 03, 2006


Deficits and National Savings

The Open CRS Network is a policy wonk's dream come true. Today's gift is the January 26th report, Federal Tax Reform and Its Potential Effects on Saving. The synopsis states one major part of the case against the Bush Administration's economic policies:
It is often argued that the saving rate in the United States is too low. Many observers suggest that the federal tax system can provide an effective way of increasing the U.S. saving rate. Indeed, one of the major directives to the President's Advisory Panel on Federal Tax Reform was to recommend modifications to the tax system that would provide simple and straightforward ways for Americans to save free of tax, which, they argue, would increase saving in the United States. The panel recommended two reform options, one based on the current income tax system and the other based on a hybrid income/consumption-based tax. The panel considered, but did not recommend, a pure consumption-based tax. Two observations can be drawn from the analysis contained in this report with respect to the effects of tax reform on the level of saving. First, public dissaving in the form of federal budget deficits reduces net national saving. So, if tax reform adds to the federal budget deficit, then, everything else being equal, tax reform would reduce net national savings. Second, even if tax reform is revenue neutral, the offsetting nature of income and substitution effects reduces the chances that changes to the tax system alone will increase saving. Indeed, because economic theory is not clear and because of the lack of compelling empirical evidence, it cannot be determined conclusively whether moving to a pure consumption tax would significantly increase the level of saving in the economy.
(My emphasis.)

The study restates one well-accepted principle pertinent to national savings rates that no one in the Bush Administration or the WSJ editorial board seems to be aware of:
[I]f there is an increase in the federal deficit then, absent any offsetting changes, net national saving will go down. Therefore, the effects of tax reform on federal revenue will have a direct bearing on the level of saving in the economy. If, under tax reform, federal revenues fall and the deficit increases, then net saving will decrease. Conversely, if federal revenues rise and the deficit decreases, then net saving will increase.
Translation: supply side economics is truly the province of (in Greg Mankiw's wonderful term) "charlatans and cranks."

The study points out:
[A]n important point with regard to the ultimate effects of tax incentives on the level of saving, a point which applies to incentives targeting both personal and business saving. If a tax incentive to promote private saving is deficit financed (the revenue loss from the tax reduction on saving is not recouped by raising other taxes), then the income effect may well dominate and the level of national saving could drop. Depending on how the tax incentive is designed, the reduction might manifest itself directly as a reduction in private saving or as a reduction in both private and public saving. (For a deficit financed tax incentive to increase total saving each dollar of tax reduction (public dissaving) would have to be matched by more than a dollar increase in private saving.)

Only if the tax incentives for saving are fully tax financed (the revenue loss from the saving incentive is made up by raising other taxes) will the income effects be eliminated. Even under these conditions, however, the overall effectiveness of the tax incentives on the level of savings is unclear.
(My emphasis.)

In other words, tax cuts will not increase the national savings rate; tax increases will. Thus:
[E]mpirical evidence regarding the effect of tax incentives on saving is inconclusive. For instance, The Economic Tax Recovery Act of 1981 reduced marginal income tax rates, expanded the availability of individual retirement accounts (IRAs), and accelerated depreciation deductions. Life-cycle models would predict that these changes would increase private savings, but that did not happen.
Finally, the study concludes that:
Because of the inconclusive empirical evidence and the theoretical ambiguities, it cannot be determined definitively that even switching to a pure consumption tax would significantly increase the level of saving in the economy.


Lies, Damned Lies, and Statistics (WSJ Edition)

Via TaxProf Blog, we have another fine example of the WSJ Editorial Board torturing statistics to prove an ideological point. The article, Tastes Great, More Filling (behind a paywall), purports to show the miracle of supply side economics because tax receipts from capital gains followed the reduction in capital gains rates. The evidence that the WSJ points to is found in a CBO study, The Budget and Economic Outlook: Fiscal Years 2007 to 2016. (The WSJ fails to note either the title of the study or the URL where it can be found. I have complained about this sort of omission before, but it appears to be typical of newspapers in general, not the WSJ in particular.)

As is frequently (always?) the case with WSJ editorials, the evidence does not support the conclusion.

The CBO report discusses capital gain realizations. That is, the amount collected by the government when capital gain assets are sold. There is no evidence that the total amount of capital gains or total tax revenues from capital gains will, in the long run, grow. In fact, the CBO report is quite explicit that:
The strong recovery in capital gains realizations since 2002 has pushed them to a level that, relative to the size of the economy, is above that implied by their past historical relationship. . . Consequently, CBO projects that, beyond 2005, capital gains will rise a bit more slowly than GDP. As it has tended to do in the past, the ratio of gains realizations to GDP is expected to gradually approach its long-run average level relative to the economy. Between 2007 and 2016, capital gains realizations are projected to grow by an average of 2.5 percent annually, lower than the 4.7 percent growth rate of both GDP and taxable personal income. Receipts from gains are expected to grow in step with gains realizations, except when tax rates increase in 2009.

The scheduled return to higher capital gains tax rates in 2009 is expected to alter the timing of realizations by encouraging taxpayers to speed up the sale of assets that will generate gains from that year to late 2008. In addition, realizations will be depressed after 2008 because the projected long-term equilibrium level of gains will be slightly lower as a result of the higher tax rates. Realizations are projected to rise by 17 percent in 2008 (boosted by the speedup in realizations), decline by 29 percent in 2009 (held down by the speedup and the adjustment to the lower equilibrium level), and rise by 21 percent in 2010 (when they rebound after the onetime speedup). After 2010, realizations are projected to rise by 3 percent to 4 percent annually through 2016.
In other words, the capital gain tax cut is much like retailers' price cutting before Christmas: Both activities raise revenue, but both also reduce profit margins. However, unlike retail purchases, sales of capital gain assets are not likely to be repeated. Think about it: you may be encouraged by price cutting to buy three instead of two shirts. But you can only realize the profit that is tied up in capital once. After you have sold the asset, there is no taxable gain left. Tax "price cutting" (i.e., the reduction in capital gain rates) only encourages a different timing of the events of realization. Thus, the net result of a decrease in capital gains taxes is that, over time, government revenues will decline. The jump in revenue that the WJS trumpets is merely an artifact of the timing of the receipt of income.

The WSJ also claims that that "stock values [increased] over that time, thanks in part to the higher after-tax return on capital induced by the tax cuts." Nothing in the report supports that conclusion. In fact, it would seem apparent that the rise in capital gain realizations in 2003 (20% over 2002) was due to the recovery from the collapse of the stock market bubble (capital gain realizations had fallen dramatically in the previous two years). If lower rates consistently caused an increase in capital gain realization, the trend would continue going forward. Yet the increase in capital gain realizations tailed off considerably after 2004 and the CBO's projections of capital gain realizations virtually fall off the table in 2006 and 2007 (2% increase in each year over the previous year). (Note: I am speaking here of capital gain realizations; any increase or decrease in capital gain tax receipts typically lags realizations by about a year.)

One positive of the WSJ's editorial positions: They're consistent. That is, they consistently mislead and in the same consistently wrong direction.

Sunday, January 29, 2006


Further Thoughts on Chawla

I've had a few additional thoughts about the Chawla case and the proposed legislative "fix" to the problem that it presents.

First, just what were the lawyers who represented the insurance company thinking? The nub of the case was Mr. Geisinger's alleged misrepresentations on his insurance application. I suspect that the "insurable interest" argument was only added later as a make-weight. Shouldn't it have occurred to someone at the insurance company that the argument, if sustained, would have cost it far more in profits on the insurance policies that it sells to fund insurance trusts than the million dollars at issue in the case?

Second, after my last posting I looked at H.B. 271, the proposed legislative response to Chawla. The bill does make it clear that trusts do have an insurable interest in the life of an insured, but only in a narrow class of cases. Specifically, in trusts established for non-business purposes, the trust is deemed to have an insurable interest in the life of the insured if:
(i) The insured is:

1. The grantor of the trust;

2. An individual related closely by blood or law to the grantor;

3. An individual in whom the grantor otherwise has an insurable interest; and

(ii) The life insurance proceeds are primarily for the benefit of the trust beneficiaries having an insurable interest in the life of the insured.
Interestingly, the language of the proposed amendment is broad enough to cover an insurance trust in some cases where the principal beneficiary is the non-married partner (gay or straight) of the grantor, since that individual will often have an insurable interest in the life of the insured. (Section 12-201(b)(3) already provides that "[f]or persons other than individuals closely related by blood or law, a lawful and substantial economic interest in the continuation of the life, health, or bodily safety of the individual is an insurable interest." Presumably, this covers non-married partners.)

However, whether an individual is a person with a "lawful and substantial economic interest in the continuation of the life, health, or bodily safety of the [insured] individual" is a question of fact. An insurance company could presumably raise questions about whether the beneficiary falls within this category if, for instance, sometime before the death of the insured, the parties had split-up and established separate places of abode.

This past week, a Maryland circuit court judge overturned Maryland's prohibition against same-sex marriage. The awkwardness of Section 12-201 with respect to non-marital partners underlines the fact that the prohibition against same-sex marriages imposes real economic and financial handicaps on same-sex couples.

Saturday, January 28, 2006


Chawla Update

In March, I commented on a decision by the U.S. District Court for Eastern District of Virginia, Chawla v. Transamerican Occidental Life Insurance Co. (February 3, 2005). In that case, the Court, gratuitously I thought, opined that the that a trust lacked an insurable interest in life of the grantor of the trust. This portion of the opinion has caused much gnashing of teeth among members of the estate planning community because insurance trusts are a commonly used estate planning mechanism and the opinion, if upheld and generally applied, would effectively prohibit their use.

On Tuesday, the Chawla case will be argued before the United States Court of Appeals. There are also two companion bills pending before the Maryland General Assembly, H.B. 271 and S.B. 300 that would remove any cloud on insurance trusts that has been cast by the opinion. If passed, the bills would modify Maryland Insurance Code Ann. Sec. 12-201 and would be apply to all trusts existing before, on, or after June 1, 2006, regardless of the effective date of the governing instrument under which the trust was created, but only as to life insurance policies that are in force and for which the insured is alive on or after June 1, 2006. In other words, the proposed statutory amendment will not affect the outcome of the Chawla case itself.

Hat Tip: Robin McDaniel Hough.

Thursday, January 26, 2006


Sloppy Is As Sloppy Does

The case of Buchbinder v. Natanzon shows that contracts can be sloppily drafted even when substantial amounts of money are involved.

A business dispute arose between Buchbinder and Natanzon. As part of the settlement of that dispute, Natanzon agreed to indemnify Buchbinder with respect to "any draw on" two letters of credit in the total amount of $1,000,000. The letters of credit were issued by Swiss bank UBS AG ("UBS") in favor of anIsraeli bank, Bank Leumi, to secure certain financial obligations of an Israeli corporation.

In late 2001, Buchbinder was asked to agree to an extension of the letters of credit through January of 2003. He agreed to the extension, but the UBS confirmation of the extension to Bank Leumi contained a typographical error stating that the extension was through December of 2003.

Subsequently, on February 5, 2003, Bank Leumi drew on the UBS letters of credit and UBS honored the draws, seizing collateral that Buchbinder had posted. Buchbinder sued UBS alleging that it had seized his collateral even though the letters of credit had expired. In settlement of that claim, UBS returned all of Buchbinder's collateral. The settlement was entered into approximately a year after the seizure of the collateral.

The suit between Buchbinder and Natanzon was initially filed requesting indemnification for the entire amount of Buchbinder's collateral that UBS had seized. However, the Buchbinder/UBS settlement left Buchbinder with an indemnification claim only for the year's worth of foregone interest and the attorneys' fees he incurred in overturning UBS's seizure of the collateral.

Judge Motz granted Natanzon's motion for summary judgment holding that the parties only intended that Natanzon's indemnification obligation only "contemplated [indemnification with respect to] timely and proper draws."
In my view, a reasonable person in the position of the parties would not have understood "any draw on the . . . letters of credit" to include demands on letters that ceased to legally exist. If that had been the meaning of the words, . . . Nantanzon would have been assuming an obligation of infinite duration, unlimited by the express written terms of the letters of credit. Reasonable business people do not assume - or expect others to assume - such obligations.
The problem with the ruling is that it undermines the intent of the indemnification provision. As I understand the facts, Buchbinder agreed to continue placing his credit and collateral at risk in order to effect the settlement with Natanzon. Absent that settlement, he would have removed himself from any risk of loss to UBS. Seen in that light, it seems reasonable to conclude that Natanzon was really agreeing to indemnify Buchbinder from any loss growing out of the relationship with UBS, since Buchbinder had only agreed to continue with that relationship as part of the settlement. Absent his obligations under the settlement agreement, he would never have been exposed to the possibility of the wrongful demand or seizure by UBS that actually occurred.

A better drafted indemnification provision could have changed the outcome of the case (e.g., "any expense, loss, or damage, including attorneys' fees or foregone interest suffered or incurred by Buchbinder with respect to any claims under the letters of credit or any extensions thereof made against him"). However, the indemnification language was hashed out in the course of the settlement of what was apparently a fairly acrimonius business dispute. In such cases, meticulous drafting is the exception rather than the rule. The Court should not have insisted, especially in the context of ruling on a summary judgment motion, on such a precisely drawn contractual provision.

Wednesday, January 25, 2006


Increased IRS Scrutiny of Family Limited Partnerships

The WSJ reports ($ubscription required) that:
The IRS is intensifying its scrutiny of family limited partnerships, a popular technique for reducing estate and gift taxes.

The heightened scrutiny comes as the Internal Revenue Service has stepped up enforcement more broadly, increasing the number of audits it performs. The agency has said it plans to focus more resources investigating taxpayers with incomes of $100,000 and above. Officials also are focusing especially on what they call abusive shelters, or transactions with no real economic purpose other than evading taxes.

As part of its deepening probe into family limited partnerships, the IRS is questioning more of these transactions and taking a harder line during audits, seeking evidence of whether they really were set up for legitimate business purposes -- or merely as an elaborate tax dodge, officials say. In an increasing number of cases, auditors are interviewing taxpayers' adult children and others involved in a partnership for details on how it was set up and run. Officials are sometimes even scrutinizing partners' medical records, or interviewing doctors, to determine if a partnership was improperly created mainly to save taxes by someone on the verge of dying.
The article suggests various ways in which FLPs can be structured to withstand scrutiny. However, at their core these methods all have characteristics that taxpayers forming FLPs often don't want, namely an entity that has an independent business purpose and that is more than an "incorporated pocketbook" for the senior member or members of the family. Once again, the most basic rule of tax law is that "pigs get fat, but hogs get slaughtered."

Hat Tip to The Law Blog.

Monday, January 23, 2006


Six of One, Half-Dozen of the Other

The recent case of Comptroller v. Blanton illustrates ways in which statutes, merely by the manner in which they are drafted, can be applied in essentially inconsistent ways. It's first necessary to have some background concerning the Maryland income tax.

Not many years ago, the Maryland income tax was pretty much a straight 5% levy. At that time, the various counties had the ability to enact "piggy-back" income taxes of up to one-half of the Maryland income tax. The county taxes were collected by the state and remitted to the appropriate counties. Subsequently, the maximum Maryland tax rate was reduced to 4.75% and the counties were allowed to set their own rates up to an additional 3.2%.

Because other states impose income taxes on income earned within their borders, there is a provision that allows a credit to Maryland residents with respect to taxes imposed by other states on non-Maryland source income. The issue in Blanton was whether this credit was applicable only to the Maryland tax or whether it applied to any county piggy-back taxes as well. The Court of Appeals held that the tax credit applied only to the Maryland income tax. Thus, Maryland residents are subject to a maximum income tax at the combined rate of (i) the higher of either the state income tax in the state in which the income is earned and (ii) the Maryland piggy-back tax.

The result can be illustrated by assuming that a Maryland resident has income from a source in another state that is taxed by that other state at a 7.5% rate. That individual will be able to offset against his or her Maryland tax an amount equal to 4.75% of the income derived from the other state. However, because the non-Maryland tax cannot be offset against the county piggy-back tax, in many cases, the total tax rate can be 10.7%, higher than the rate imposed by either state.

However, the result with respect to Maryland income of non-Maryland residents is quite different. The Maryland income tax applies to all Maryland income of non-residents and to all income of residents. However, the county piggy-back taxes apply only to the income of the residents of the respective counties. Thus, if a non-resident has Maryland income, he or she only pays the Maryland tax, not a county piggy-back tax. In most cases, the non-Maryland resident will be allowed a credit in his or her home state in an amount equal to the Maryland tax paid. While if the domicile of the taxpayer is Florida or one of the other states without personal income tax, the maximum tax imposed on the income is 4.75%, the virtually every other case the maximum rate of tax will not exceed the greater of the maximum Maryland tax rate or the maximum tax rate imposed in the taxpayer's state of domicile.

The manner in which the statute and the credit provision is structured results in Maryland residents being potentially subjected to higher rates of tax from income earned in other states, while residents of those other states pay a lower rate of taxes on Maryland source income. In fact, in some cases (e.g., where the taxpayer is a resident of Florida), the tax rate will be substantially lower on Maryland income earned by non-Maryland residents than on Maryland residents.

The decision in Blanton, as a matter of statutory construction, is clearly correct. However, it leads to a result that puts Maryland residents at a disadvantage. The irony is that the tax scheme does not need to lead to an anomalous result. There's an easy fix.

All that is necessary is for the Maryland tax to be restructured to provide that the tax rate is 7.95%. Each county could be allowed to enact a piggy-back tax of up to 3.2%. The county tax would be a credit against the state tax. Non-Maryland residents who have Maryland income would pay a tax of 7.95% on their Maryland source income, since they would pay no county tax, they would not be able to use the "county tax credit." Maryland residents would pay tax at the rate of no more than the 7.95%, which is either what most are either paying now or close to it.

On the other hand, Maryland residents would be allowed a credit against their Maryland tax of up to 7.95% of the tax paid to another state. Thus, the tax on non-Maryland income of Maryland residents would never be more than the greater of (i) the Maryland tax rate or (ii) the tax rate in the state where the income is earned.

Let me summarize: By changing the manner in which the statute is drafted, no Maryland voter would pay more tax on his or her income and many would pay less. The loss occassioned by the reduction in taxes on Maryland income would be offset by an increase in taxes on non-Maryland residents. In many, if not most, cases, this tax increase would not be borne by the non-Maryland resident, but by their home states.

What's not to like?

Sunday, January 22, 2006


If You Got A Warrant, I Guess You're Gonna Come In

Bob Ambrogi reports that:
News this week that the Justice Department is asking a federal court to compel Google to turn over records of millions of its users' search queries is shocking and disturbing. Worse yet, America Online, Yahoo and MSN have already complied with the subpoena.

For anyone who would rather not leave behind a trail of their search queries for government investigators to examine, there is a way to search Google and Yahoo anonymously -- it is called Scroogle. Its search proxy sends your queries through Google and returns the results free of ads and cookies, circumventing Google's tracking.

To learn more about Google and privacy, visit Scroogle's companion site, Google Watch.
I first went to Scroogle and learned that it allowed both Google and Yahoo searches without any tracking record. Interestingly, the site also recommended Clusty, which it states "has better results than Google and doesn't track you." Both Scroogle and Clusty have search icons that can be added to the Firefox search bar.

I then when to Google Watch. That site made statements about GMail which, if true, are also troubling:
Google offers more storage for your email than other Internet service providers that we know about. The powerful searching encourages account holders to never delete anything. It takes three clicks to put a message into the trash, and more effort to delete this message. It's much easier to "archive" the message, or just leave it in the inbox and let the powerful searching keep track of it. Google admits that even deleted messages will remain on their system, and may also be accessible internally at Google, for an indefinite period of time. For a few months they showed a note saying that messages left in the trash folder for 30 days would be automatically deleted, but many users reported that this never happened. Now that message, which is still present for the spam folder, is gone from the trash folder. Google wants very much to get to know you better.
* * * * *
After 180 days in the U.S., email messages lose their status as a protected communication under the Electronic Communications Privacy Act, and become just another database record. This means that a subpoena instead of a warrant is all that's needed to force Google to produce a copy. Other countries may even lack this basic protection, and Google's databases are distributed all over the world. Since the Patriot Act was passed, it's unclear whether this ECPA protection is worth much anymore in the U.S., or whether it even applies to email that originates from non-citizens in other countries.
I don't know whether this is true, but, as a protective matter, I fully intend to not to keep anything on my GMail account for more than 180 days.

Saturday, January 21, 2006


The Spies Who Love Me

The Federation of American Scientists has published on its website the National Security Agency's Redacting with Confidence: How to Safely Publish Sanitized Reports Converted From Word to PDF. I suspect that the practices set forth in the report can be applied to WordPerfect documents as well. Now there's no excuse for sending out pdf documents with metadata.

It is questionable whether it is unethical to read the other parties' metadata when a document has been sent to you by the opposing side. However, the sender should consider the malpractice implications of failing to sanitize documents.

Hat Tip to Boing Boing.


Information Overload?

At what point does the government have too much personal information? Even if it has a legitimate use for the personal information, does the danger of allowing government officials to have the information at their fingertips outweigh these legitimate benefits? These questions are raised by the following story from Tax Analysts:
IRS Fleshes Out Data Warehouse Plans; Outsiders Raise Concerns

In a January 20 phone interview with Tax Analysts, IRS Electronic Tax Administration Director Bert DuMars dismissed privacy concerns while laying out the details of a potential IRS data warehouse.

DuMars told Tax Analysts that the IRS has already begun studying the costs and benefits associated with creating a central database. It would house taxpayer information from Form W-2 as well as the "families" of Forms 1098 and 1099. The "data warehouse" would serve as a single collection point for the forms and would be made available to other government entities such as the Social Security Administration and state agencies.

"We’re not the only ones who need this information," he said.

DuMars told Tax Analysts that a data warehouse would not tread on any section 6103 disclosure rules because it would be shared only with entities that already have access to the data.

"I don't see a problem with [disclosure]," he said. "That’s not what we're concerned about here."

DuMars said at least two benefits could result from creating a database. Putting all the information in one central place would save time and money for the IRS and other agencies by replacing myriad separate and convoluted information-sharing processes. It would also make the information readily available to taxpayers. According to DuMars, if the data warehouse had been in place when Hurricane Katrina hit, thousands of taxpayers who lost documents would now be able to retrieve their information.

Several former tax administrators contacted by Tax Analysts raised concerns about the prospect of an IRS data warehouse, arguing that it could put the IRS on a slippery slope.

"The more convenient the information is, the more risk there is of losing it -- because you make it available to more people," said former IRS Commissioner Sheldon Cohen.

Cohen and others said that while a database might start with a limited number of forms, it's a short leap from there to adding more documents and information.
Over time, like most Americans, I've gotten used to having information that used to be private or semi-private open to ready public inspection. That is, there was a great deal of material (e.g., the valuation of your home for property tax purposes, court records, etc.) that was always open to public inspection, but it used to take some degree of energy to seek out the information. Today, however, that information is frequently only a mouse click away.

The principle invoked by the IRS here is that the proposal does not increase the number of people or agencies that have access to the information. Instead, the database would simply make it easier for those who are already authorized to view the data to access it. The reason that the proposal is troubling is that the obvious increased efficiency in the ability to access the data can be used for ill as well as good.

The story is also covered by the Center for Tax Studies weblog, here.

Friday, January 20, 2006


Don't Take My Wife, Please?

With apologies to the late Henny Youngman, there is this article from the New York Post via the California Estate and Business Law Blog:
Couples who stay married through thick and thin accumulate twice as much personal wealth as people who get divorced or remain single, a new study reveals.

In fact, divorce reduces a person's wealth by about three-quarters, compared to that of someone who never marries. And people who decide to split up even start seeing their finances erode years before the divorce is finalized.

"Getting married and staying married is a wonderful way to increase your wealth — but the key is stay married," research scientist Jay Zagorsky of Ohio State University told the Post.
Getting married and staying married may be positively correlated to increasing wealth, but it may not necessarily be a "wonderful way." As the aforementioned Mr. Youngman once said: "I've been married for 49 years. Where have I failed?"

Wednesday, January 18, 2006


Grover Norquist and the Tax Code

In October, I asked: Did Grover Norquist Commit Tax Fraud? The information that is publicly available is still too limited to allow one to definitively answer that question. However, the facts that are publicly available point to systematic violations by Norquist of various provisions of the Internal Revenue Code.

Case in point. In an article entitled The Pimping of the President, the Texas Observer gives a detailed account of how Jack Abramoff and Norquist got paid by two Native American tribes to provide a personal audience with President Bush. There seems to be some question as to who was in attendance, but there is no question that Norquist's organization, Americans for Tax Reform, recieved a $25,000 payment for Norquist's efforts. (A facsimile of the check accompanies the article.)

In my October posting, I noted that there are two entities controlled by Norquist that go by the name "Americans for Tax Reform." One is a 501(c)(3) charitable foundation, the other a 501(c)(4) "civic organization." The principal difference between the two classifications for the purposes of my October discussion was the fact that more stringent limits are imposed on the amount of lobbying expenses that the 501(c)(3) foundation can incur. However, there is an important limitation that applies to both types of entity. Specifically, neither a 501(c)(3) or a 501(c)(4) entity can be what is termed "an ACTION organization," although that term of art applies more broadly (and is thus more restrictive) with respect to 501(c)(3) entities than 501(c)(4) entities.

With respect to 501(c)(3) organizations, there are three forbidden areas:
  • Legislative lobbying efforts;

  • Participation in campaigns for public office; and

  • As described in Treas. Reg. Section 1.501(c)(3)-1(c)(3)(iv):
[The organization's] main or primary objective or objectives (as distinguished from its incidental or secondary objectives) [cannot] be attained only by legislation or a defeat of proposed legislation; and (b) [and it cannot] advocate[], or campaign[] for, the attainment of such main or primary objective or objectives as distinguished from engaging in nonpartisan analysis, study, or research and making the results thereof available to the public. In determining whether an organization has such characteristics, all the surrounding facts and circumstances, including the articles and all activities of the organization, are to be considered.
A 501(c)(4) entity is only an ACTION organization subject to losing the benefits of Section 501 if it engages in active participation in campaigns for public office. I will, as lawyers are wont to say, assume, arguendo, that Norquist honored the distinctions between the types of activities that 501(c)(3) organizations are prohibited from engaging in and the more broader range of activities allowed to 501(c)(4) organizations. However, even allowing Norquist that assumption does not get him off the hook.

The reason is that neither 501(c)(3) nor 501(c)(4) organizations can be "organized or operated for profit." (The term is from 501(c)(4), but but 501(c)(3) organizations are subject to limitations that are similar, but even more limiting.) Norquist's actions as detailed in the Texas Observer story show that he was using Americans for Tax Reform, whether in its 501(c)(3) or 501(c)(4) incarnation, as his personal business vehicle.

By way of example, the visit to the White House took place in May of 2001. The check in consideration for Norquist's efforts was drawn in the next month. This raises two possibilities.

First, Americans for Tax Reform may have been engaged in a profit-making endeavor. If that was the case, there was a violation of the rules under Section 501(c).

Alternatively, the lobbying was a business activity that Norquist personally engaged in. If that was the case, Norquist would be deemed to have "constructively received" the $25,000 check. In that event, he should have reported the $25,000 payment as income on a Schedule C on his Form 1040 for the year. He would not have been able to claim a deduction for the transfer of the funds to Americans for Tax Reform, regardless of whether the entity that the funds found their way into was the 501(c)(3) or 501(c)(4) entity.

Let me reiterate: There are not yet sufficient facts on the public record to prove that Norquist engaged in tax fraud. However, it is difficult to believe that the actual transaction reported in the Texas Observer was an isolated incident. Rather, it appears that Norquist, and probably others, used 501(c)(3) and 501(c)(4) entities to engage in the "business" of partisan politics. That business made them money, as their influence and the funding of their controlled 501(c) entities grew.

To determine whether a violation of the 501(c) rules occurred, the transactions engaged in cannot be viewed in isolation. Rather, "all the surrounding facts and circumstances, including . . . all activities of the organization, are to be considered." I assume that this is an effort that the federal prosecutors are currently undertaking.

Hat Tip: Mark Kleiman at The Reality-Based Community.


Damn It Jim, I'm A Tax Lawyer Not An Actor

It has been reported that William Shatner has sold a kidney stone to an on-line gambling casino, GoldenPalace.com, for $25,000, with the proceeds to go to a charity, Habitat for Humanity. Of course, the question that immediately comes to everyone's mind (?) is "What are the tax implications?"

Presumably, Shatner either deeded the actual stone to the charity or entered into an agreement with the casino that it would sell the stone and pay all proceeds to the charity. Thus, Shatner will not take any amount of the proceeds into income.

Arguably, he may be entitled to a small charitable tax deduction for the stone. The net amount of any charitable deduction for "self-created" property (I think we all can agree that the stone qualifies as "self-created") is measured by reducing the value of the item (i.e., $25,000) by the amount of ordinary income that the donor would have taken into account if he sold the valuable stone. One might think that this would mean that there is no charitable deduction since the entire amount that Shatner would have received if he had sold the stone would be subject to taxation at ordinary rates. However, this ignores the basis issue. If Shatner paid out of his own pocket for the medical care necessary to "produce" the stone, that amount would conceivably be deductible.

This, of course, is a detour. Tomorrow, back to real tax and business issues. In other words, all things must pass.

Sunday, January 15, 2006


How Smart Are We?

On the heels of the CRS study that shows that we cannot "save" ourselves out of budget deficits (my comments here), is a report, The Economic Costs of the Iraq War: An Appraisal Three Years After the Beginning of the Conflict, by Linda Bilmes and Joseph E. Stiglitz. That report serves only to emphasize the impossibility of regaining our budgetary and economic footing without raising additional taxes.

In the introduction, the authors note that:
Three years ago, as America was preparing to go to war in Iraq, there were few discussions of the likely costs. When Larry Lindsey, President Bush's economic adviser, suggested that they might reach $200 billion, there was a quick response from the White House: that number was a gross overestimation. Deputy Defense Secretary Paul Wolfowitz claimed that Iraq could "really finance its own reconstruction," apparently both underestimating what was required and the debt burden facing the country. Lindsey went on to say that "The successful prosecution of the war would be good for the economy."

Many aspects of the Iraq venture have turned out differently from what was purported before the war: there were no weapons of mass destruction, no clear link between Al Qaeda and Iraq, no imminent danger that would warrant a pre-emptive war. Whether Americans were greeted as liberators or not, there is evidence that that they are now viewed as occupiers. Stability has not been established. Clearly, the benefits of the War have been markedly different from those claimed.

So too for the costs. It now appears that Lindsey was indeed wrong—by grossly underestimating the costs. Congress has already appropriated approximately $357 billion for military operations, reconstruction, embassy costs, enhanced security at US bases and foreign aid programs in Iraq and Afghanistan. This total, which covers costs through the end of November 2005, includes $251bn for military operations in Iraq, $82bn for Afghanistan and $24bn for related foreign operations, such as reconstruction, embassy safety and base security. These costs have been rising throughout the war. Since FY 2003, the monthly average cost of operations has risen from $4.4bn to $7.1 bn – the costs of operations in Iraq have grown by nearly 20% since last year (whereas Afghanistan was 8% lower than last year). The Congressional Budget Office has now estimated that in their central, mid-range scenario, the Iraq war will cost over $266 billion more in the next decade, putting the direct costs of the war in the range of $500 billion.

These estimates, however, underestimate the War's true costs to America by a wide margin. In this paper, we attempt to provide a range of estimates for what those costs have been, and are likely to be. Even taking a conservative approach, we have been surprised at how large they are. We can state, with some degree of confidence, that they exceed a trillion dollars.
(Footnotes omitted, emphasis added.)

The report provides a valuable corrective to the truly abominable reporting by most mass news organizations of the economic issues surrounding the war. Thus:
The costs of the war in Iraq that have been reported in the media have almost exclusively focused on one type of cost – the $251bn in cash that the government has spent on combat operations since the invasion of Iraq in March 2003. This is an important element of the financial cost but it is only the tip of a very deep iceberg.

Currently the US is spending about $6bn per month on operations in Iraq. However, there are additional costs to the government – over and above this number. These include disability payments to veterans over the course of their lifetimes, the cost of replacing military equipment and munitions which are being consumed at a faster-than-normal rate, the cost of medical treatment for returning Iraqi war veterans, particularly the more than 7000 servicemen with brain, spinal, amputation and other serious injuries, and the cost of transporting returning troops back to their home bases. The Defense Department, for which expenditures not directly appropriated for Iraq have grown by more than 5% (CAGR) since the war began, has also spent a portion of this increase on support for the war in Iraq, including significantly higher recruitment costs, such as nearly doubling the number of recruiters, paying recruitment bonuses of up to $40,000 for new enlistees and paying special bonuses and other benefits, up to $150,000 for current troops that re-enlist. Another cost to the government is the interest on the money that it has borrowed to finance the war.

Although it is difficult to estimate these costs precisely, we can use current and expected troop deployment to make a reasonable projection of the likely costs. Looking purely at direct budgetary costs to the taxpayer, we estimate that the total cost of the Iraq war is in the range of $750 billion to $1.2 trillion, assuming that the US begins to withdraw troops in 2006 and maintains a diminishing presence in Iraq for the next five years. We have looked at the budgetary cost both including and excluding the cost of interest on the debt. We have also adjusted this cost for economic factors, as outlined in section two. Under any reasonable set of assumptions, the cost of the war even without considering the macroeconomic costs – is more than double the current number provided by the Administration.
(Emphasis in the original.)

In concluding, the report states that:
Though we have suggested that many of the costs were within the range of what could have been anticipated, we have not sought in this paper to ascertain whether on the basis of the information available, the Administration could have made more reliable estimates. We do not address the question of whether the disparity between the predicted numbers and the actual numbers is a result of a deliberate attempt of the Administration to mislead the American people on the cost of the war, or of incompetence, going to War with information of low reliability and with best estimates that were far from the mark. In response to accusations about the existence of weapons of mass destruction and the connection with Al Qaeda, the Administration has been adamant that it did not intentional deceive the American people; it prefers charges of incompetence to those of malevolence. We have not attempted to ascertain the relative role of each in the failure to provide the American people with an accurate cost of the venture. At the very least, though, honesty would have required laying out the various scenarios, even if it attached low probabilities to those that in fact turned out to be the case.

Americans could, and should have asked, are there ways of spending that money that would have enhanced our long run well being—and perhaps even our security—more. Take the conservative estimate of a trillion dollars. Half that sum would have put social security on a firm grounding for the next seventy-five years. If we spent even a small fraction of the remainder on education and research, it is likely our economy would be in a far stronger position. If some of the money spent on research were devoted to alternative energy technologies, or to providing further incentives for conservation, we would be less dependent on oil, and thereby more secure; and the lower prices of oil that would result would have obvious implications for the financing of some of the current threats to America’s security. While we may not know what causes terrorism, clearly the desperation and despair that comes from the poverty that is rife in so much of the Third world has the potential of providing a fertile feeding ground. For sums less than the direct expenditures on the war, we could have fulfilled our commitment to provide .7% of our GDP to help developing countries—money that could have made an enormous difference, for the better, to the well being of billions today living in poverty. We could have had a Marshall Plan for the Middle East, or the developing countries, that might actually have succeeded in winning the hearts and minds of those in the Middle East.

What is clear is that the Administration's original estimates were strikingly low. Would the American people have had a different attitude towards going to war had the known the total cost? Would they have thought that there might be better ways of advancing the cause of democracy or even protecting themselves against an attack, that would cost but a fraction of these amounts? In the end, we may have decided that a trillion dollars spent on the War in Iraq was better than all of these alternatives. But at least it would have been a more informed decision than the one that was made. And recognizing the risks, we might have conducted the War in a manner different from the way we did.
(Footnotes omitted.)

Recently, the "debate" over the war in Iraq, such as it is, has focused on only two aspects of the war.

The first is the "Were we lied to?" issue. That is, did the Bush Administration intentionally cook the information books in pushing for war.

The second aspect of the debate has been the "Well we're here now, how do we play the ball as it lies?" issue. That is, Administration supporters, on one side, paint those who want to terminate U.S. involvement quickly as defeatists who want to snatch defeat from the jaws of victory. Opponents of the war, on the other hand, sound the "We're waist deep in the Big Muddy and the Big Fool tells us to push on" theme.

To say the least, the debate has been less than edifying. I have long advocated the theory that the Internet, by putting an incalculable wealth of information at our fingertips, makes us smarter. However, my theory seems to be challenged by the reality that simple facts (e.g., the discretionary portions of the federal budget do not contribute to the budget deficit in a significant way) never seem to gain a foothold in the public discourse. Really complex questions (e.g., can we justify the costs of continuing the venture in Iraq when it weakens our ability to deal with foreign policy problems such as Iran and North Korea) seem hopelessly beyond our abilities.

Hat Tip: beSpacific.

Saturday, January 14, 2006


Due Process and Tax Sales

Tuesday, the Supreme Court will hear arguments in Jones v. Flowers, concerning the type of notice that is required to meet due process requirements in the case of tax sales of real property. The following summary is from the discusson of the case on the website of the Legal Information Institute of Cornell University:
In 1967 Gary Jones purchased a house in Little Rock, Arkansas. When he and his wife separated in 1993, his wife stayed in the house and he moved to a new address. Jones did not notify the tax authority of his new address. After both Joneses failed to pay taxes on the house, the Commissioner of State Lands sent a notice to Gary Jones' last known address via certified mail. The notice stated that the property would be subject to a public sale if Jones did not pay the delinquent taxes and penalties. The notice returned to the Commissioner as "unclaimed." Later, a newspaper announced the public sale of the Jones's house. Jones did not respond to the publication. When Linda Flowers offered to buy the property, the State again sent notice to Jones at his last known address via certified mail. This notice also was returned unclaimed. In 2003 Flowers bought the house. See Jones v. Flowers, No. 04-449, 2004 WL 2609800 (Ark. Nov. 18, 2004).

Jones then filed a complaint, claiming that the sale violated his rights under the due process clause of the Constitution because he never received actual notice of the tax sale or of his right to redeem. The trial court upheld the sale, finding that the State complied with due process by sending notices via certified mail to Jones’s last known address. See id.

The Arkansas Supreme Court affirmed the trial court's holding. The court cited Mullane v. Central Hanover Bank & Trust Co., 339 U.S. 306, 214 (1950), which held that due process does not require actual notice, and that notice is sufficient if it is "reasonably calculated, under all the circumstances, to apprise interested parties of the pendency of the action and afford them an opportunity to present their objections." Based on this standard, the court reasoned that the State was not required "to conduct a reasonable search of public records in an attempt to ascertain Mr. Jones's correct address before selling his property." The court found that the State only needed to send notice to Jones's last known address, which it did. See Jones v. Flowers, No. 04-449, 2004 WL 2609800 (Ark. Nov. 18, 2004). The court accordingly concluded that the sale was valid because Jones received adequate notice for due process purposes. See id.

The Supreme Court agreed to review the case to resolve the split among state and federal courts on the question of what steps the government must take to locate property owners before taking their property.
A more complete discussion of the case, including the policy implications and links to the briefs can be found at the LII link above.


Bureaucracy Is Everywhere

I've sometimes regretted that I did not become a comedy writer. Just think what I could do with the story in today's NYT that Jose Padilla had filled out an application to become a member of Al Qaeda. What information was requested?
  • Are you willing to become a martyr?

  • Do you have experience in small arms?

  • Do you know how to fly a jet airliner?

  • Any known allergies?

Friday, January 13, 2006


Notes On Federal Spending

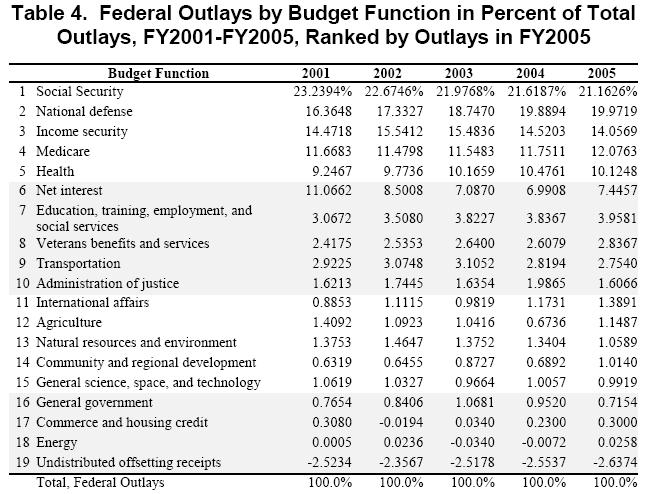
There's another good CRS report out, this time on federal spending. The report, Federal Spending by Agency and Budget Function, FY2001-FY2005, shows that non-military discretionary spending is fairly insignificant in the overall budgetary framework. Simply put, unless entitlements and the military budget are cut drastically, we cannot "save" ourselves out of the current budget deficit.

The top six budget functions, combined, accounted for 86.1% of federal expenditures in 2001 and 84.8% of federal expenditures in 2004. Five of the six (Social Security, Income Security (which includes unemployment compensation, food and nutritional assistance, and federal civilian and military retirement), interest on the federal debt, Medicare, and health benefits (which include Medicaid) are not discretionary. Moreover, as the report notes, "much less than the 30% to 40% of the budget considered discretionary can be reduced through appropriations alone" because:
Even the 30% to 40% of the budget that is subject to annual appropriations is not completely discretionary. Much of the annual appropriated amounts are necessary to fulfill legal commitments that the government had entered into in previous time periods, such as contracts or other obligations. Unless Congress and the President are willing to eliminate programs and the federal employees that run them, a certain amount of the annual appropriations are needed for federal salaries. In addition, approximately half of the annual appropriated amount goes to defense spending, which during a time of war is difficult to reduce.
The report has a table which shows federal outlays by budget function expressed as a percent of total outlays:

(Click to enlarge.)

Of course, there are winners and losers. Thus, there has been a dramatic increase in expenditures on the Executive Office of the President from $246 million to $7.725 billion. (For you math majors, that means that the amount of spending in 2005 was 31.4 times that for 2001.) Of course, there had to be some belt-tightening. The EPA, for instance, was held to an increase of only a little over 7% for the period covered, with spending actually falling from 2004 to 2005.

The summary of the report has it right:
Without a substantial reordering of the public's priorities as reflected in the government's allocation of resources, most spending reduction efforts seem destined to remain relatively small and, thus, are likely to have a limited effect on overall federal spending.
Hat tip to beSpacific.

Thursday, January 12, 2006


Wal-Mart Medical Insurance Bill ERISA Preemption Analysis

Paul M. Secunda of Workplace Prof Blog gives this analysis of whether ERISA preempts the Wal-Mart Medical Insurance Bill now before the Maryland General Assembly:
My first impression conclusion here is probably the same conclusion I came to [in an earlier post on bills pending in Massachusetts and Illinois which would require employers to foot the bill for employee health care through a "pay-or-play system."]: it all depends on whether Wal-Mart self-insures its health plans. If it does, the deemer clause should lead to ERISA preemption of the state law; if not (that is, it insures its health plans through another company), it should be saved from ERISA preemption as a law that regulates insurance under ERISA's Savings Clause.
As of this evening, one house of the General Assembly has overriden Gov. Ehrlich's veto of the bill and the override measure is moving to the other house.

Hat Tip to the WSJ's Law Blog.

Update

Whoops!! I should have checked the wire services before I finished my post. Even before I finished the post, the Maryland General Assembly overroad Gov. Ehrlich's veto of the Wal-Mart medical insurance tax bill.


Poetic Tax Law

Whoever said that tax law does not appeal to our higher faculties should read this by Jim Scheinkman:
To withhold, or not to withhold: that is the question:
Whether 'tis nobler in the mind to suffer
The slings and arrows of outrageous penalties,
Or to take arms against a sea of business situs tests,
And by opposing end them? To withhold: to report;
No more; and by tax reporting to say we end
The heart-ache and the thousand tax audits
That aggressive report positions is heir to, 'tis a consummation
Devoutly to be wish'd. To withhold, to report;
To remit: perchance to 1099: ay, there's the rub;
For in that reporting what dreams may come
When we have shuffled off all of our income,
Must give us pause: there's the respect
That makes calamity of so long statute of limitations;
For who would bear the whips and scorns of the IRS,
The tax agent's wrong, the taxpayer's form over substance,
The pangs of despised Treasury Regulations, the law's delay,
The insolence of the FTB and the spurns
That patient merit of the unworthy tax returns,
When he himself might his quietus make
With a bare bodkin? who would fardels bear,
To grunt and sweat under a weary tax code,
But that the dread of something after April 15,
The undiscover'd revenue ruling from whose bourn
No advisor returns, puzzles the analysis
And makes us rather bear those taxes we have
Than evade others that we know not of?
Thus Circular 230 Disclaimers does make cowards of us all;
And thus the native hue of income recognition
Is sicklied o'er with the pale cast of AMT,
And enterprises of great adjusted gross income
With this regard their cash flow turn awry,
And lose the name of after tax profit.--Soft you now!
The fair Ophelia! Nymph, in thy orisons
Be all my tax schemes remember'd.
I think I need a vacation.....
Hat tip to Bahar Schippel.